Before you visit a single property, know how big a loan the bank will give you. It decides your budget more than anything else.
The rule banks use
Lenders look at how much of your monthly income goes to EMIs. This is called FOIR (fixed obligations to income ratio). Most banks keep all your EMIs, including the new home loan, to about 50% of your take-home pay. Some go up to 55–60% for higher incomes.
So the bank works backwards: half your income is the most EMI you can pay, and that EMI decides the loan.
Loan you can expect at different incomes
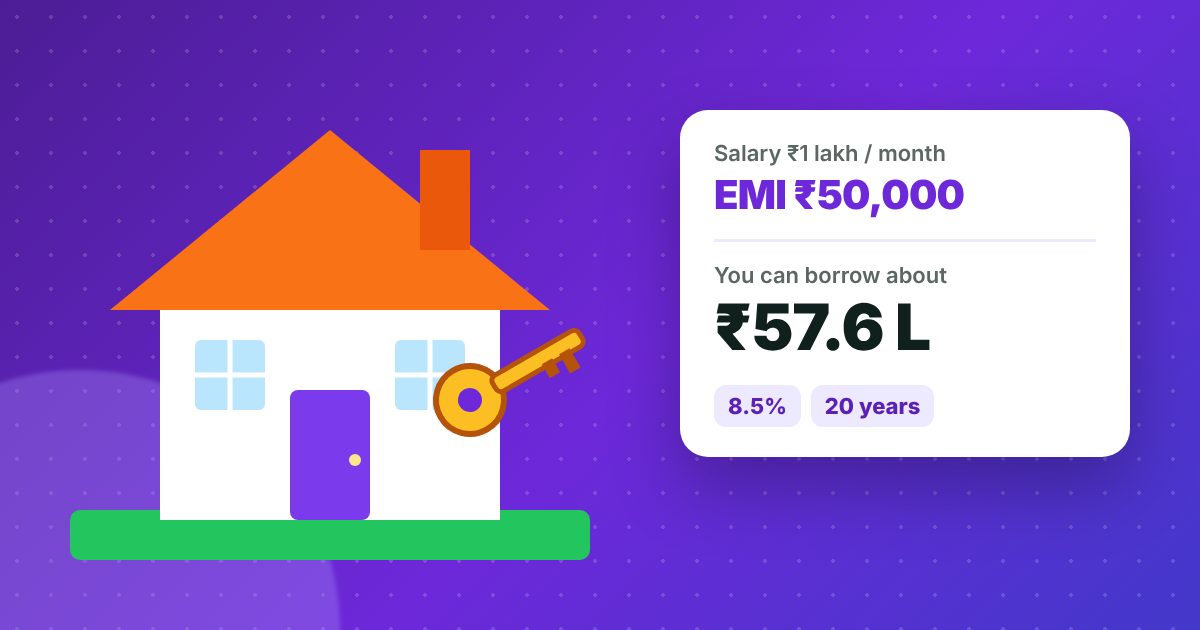
At 8.5% for 20 years, with no other EMIs and 50% FOIR:
| Take-home per month | Max EMI | Loan amount | Property you can buy |
|---|---|---|---|
| ₹50,000 | ₹25,000 | about ₹28.8 lakh | about ₹32 lakh |
| ₹75,000 | ₹37,500 | about ₹43.2 lakh | about ₹54 lakh |
| ₹1,00,000 | ₹50,000 | about ₹57.6 lakh | about ₹72 lakh |
| ₹1,50,000 | ₹75,000 | about ₹86.4 lakh | about ₹1.15 crore |
Why you need a down payment
RBI caps how much of the property price a bank can lend (the loan-to-value limit):
- Loans up to ₹30 lakh: up to 90% of the property value
- ₹30–75 lakh: up to 80%
- Above ₹75 lakh: up to 75%
So on a ₹72 lakh flat you must pay at least ₹14.4 lakh yourself, plus stamp duty and registration, which banks usually don't fund.
What reduces your eligibility
- Other EMIs. A ₹15,000 car EMI on a ₹1 lakh income cuts the home loan from about ₹57.6 lakh to about ₹40.3 lakh.
- Age. Most banks want the loan repaid by 60 (or 65–70 for some self-employed borrowers), so the tenure gets shorter as you get older.
- Low credit score. A score below about 700 can mean a higher rate or a smaller loan.
Five ways to borrow more
- Add a co-applicant with an income, such as your spouse. Their income is added to yours.
- Choose a longer tenure. The same ₹50,000 EMI supports about ₹65 lakh over 30 years instead of ₹57.6 lakh over 20. You'll pay more interest, so prepay when you can.
- Close small loans first, especially personal loans and credit card EMIs.
- Check your credit report for mistakes before applying.
- Compare lenders. A lower rate directly raises how much the same EMI can borrow.
Banks set their own FOIR and rules, so treat these numbers as a guide and confirm with your lender.